
Coverage that holds for contractors.ranchers.restaurants.truckers.families.
Business insurance, explained in plain words, by someone in San Antonio. We compare real options from multiple A-rated carriers and read the whole policy with you.
Insurance for the work Texas actually does.
Commercial insurance is our main focus. Personal lines are how we look after the people behind those businesses.
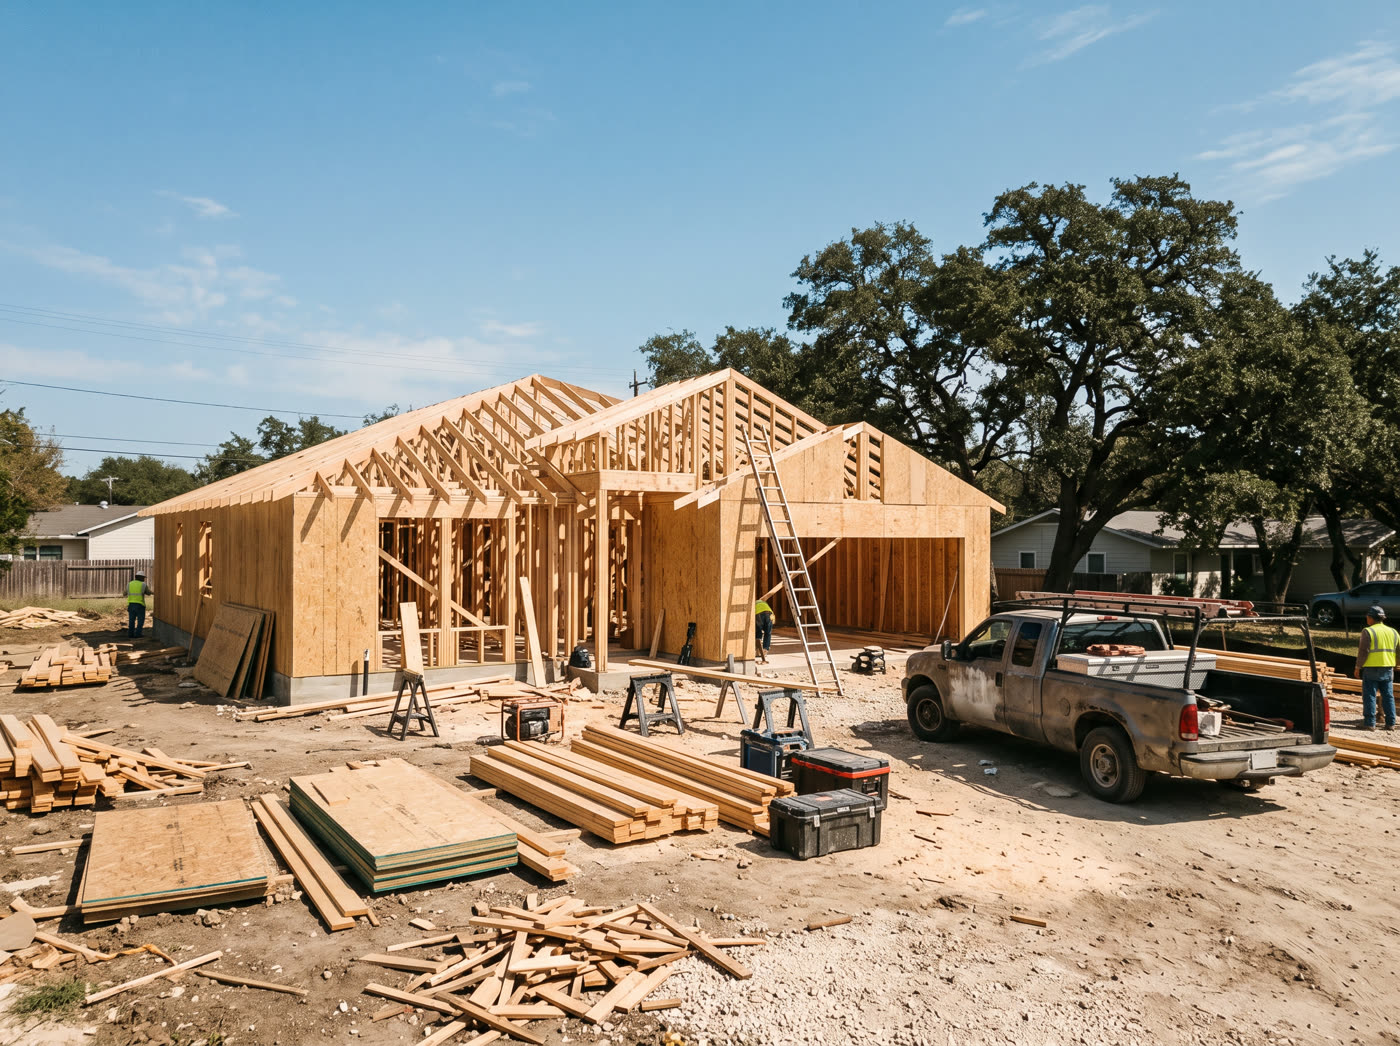
Job sites and trucks
General liability, tools and equipment, commercial auto, workers' comp.
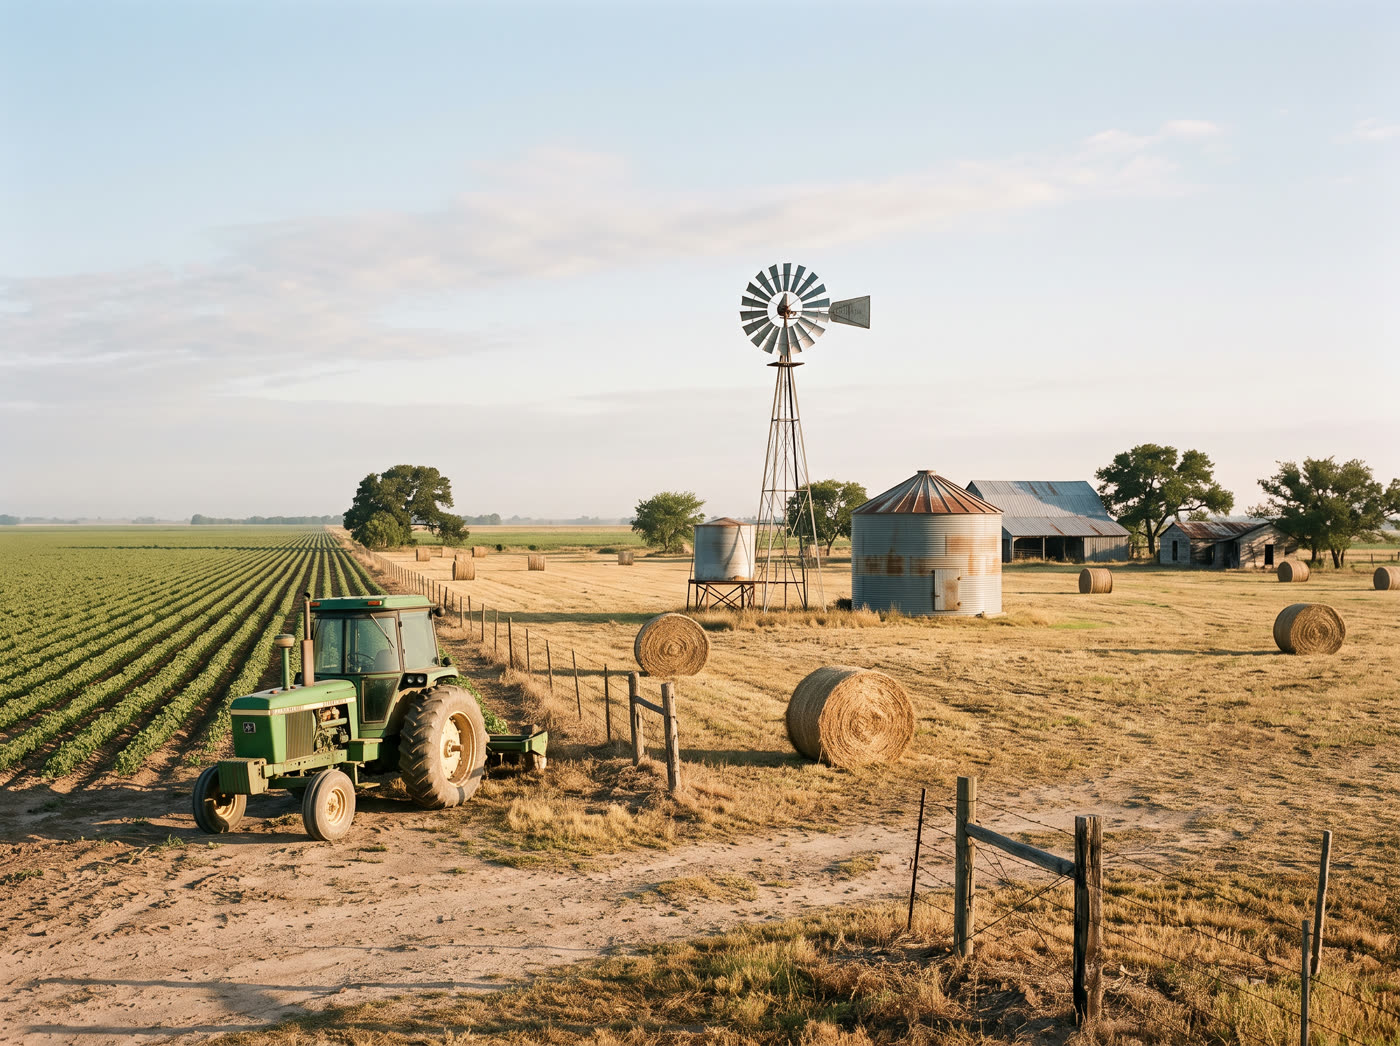
Land, livestock, equipment
One policy for the house, barns, machinery and liability.
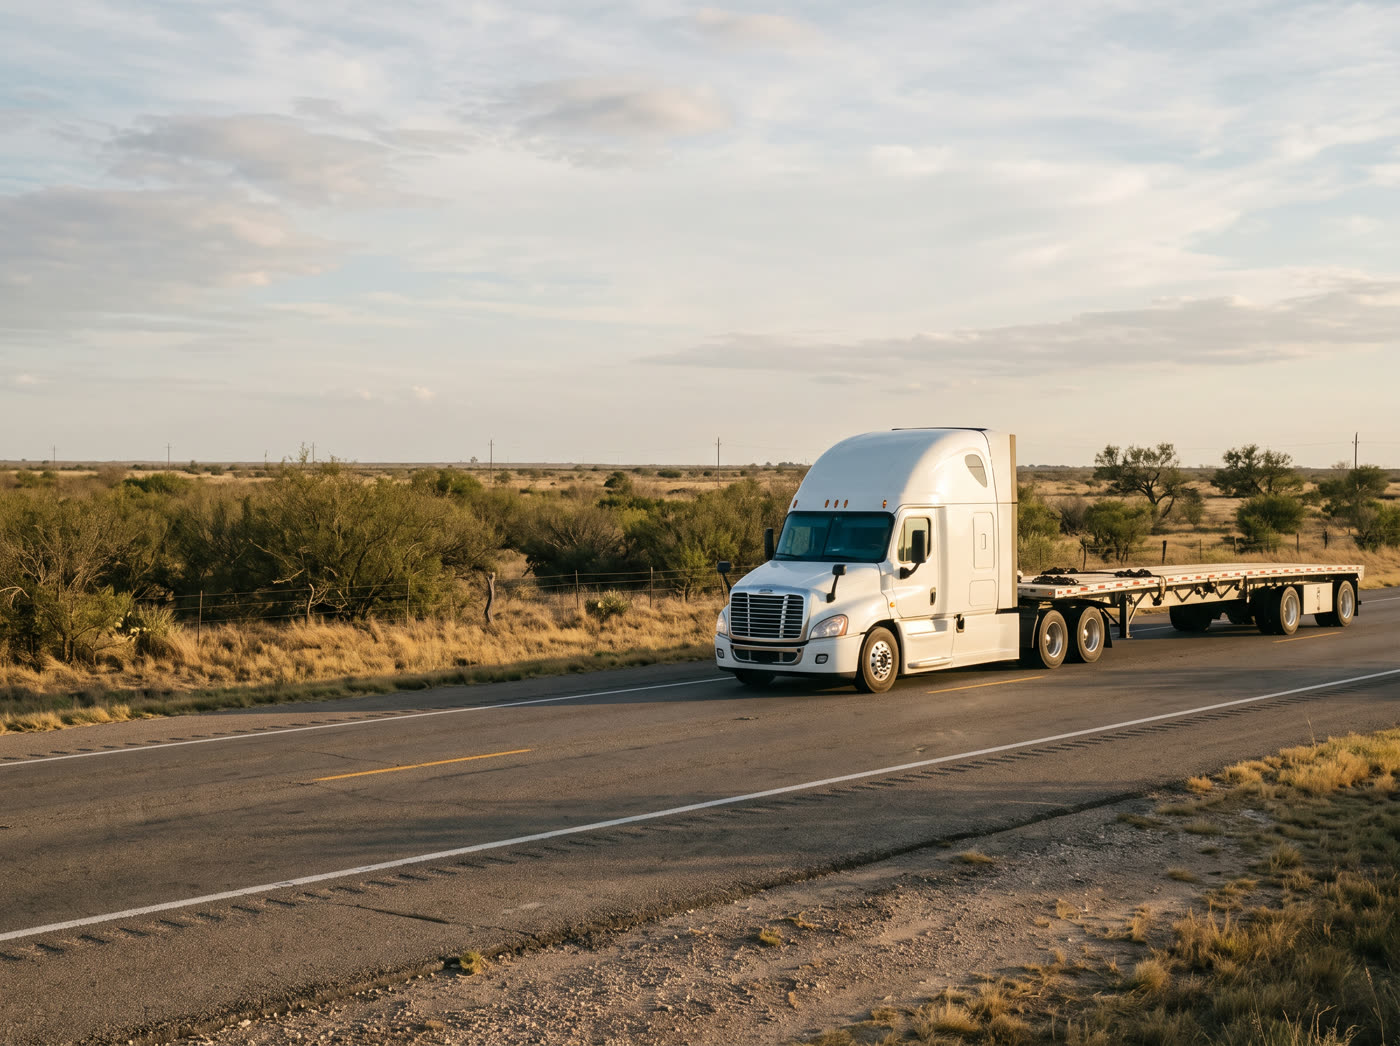
On I-35, I-10 and beyond
Primary liability, cargo, physical damage, filings handled.
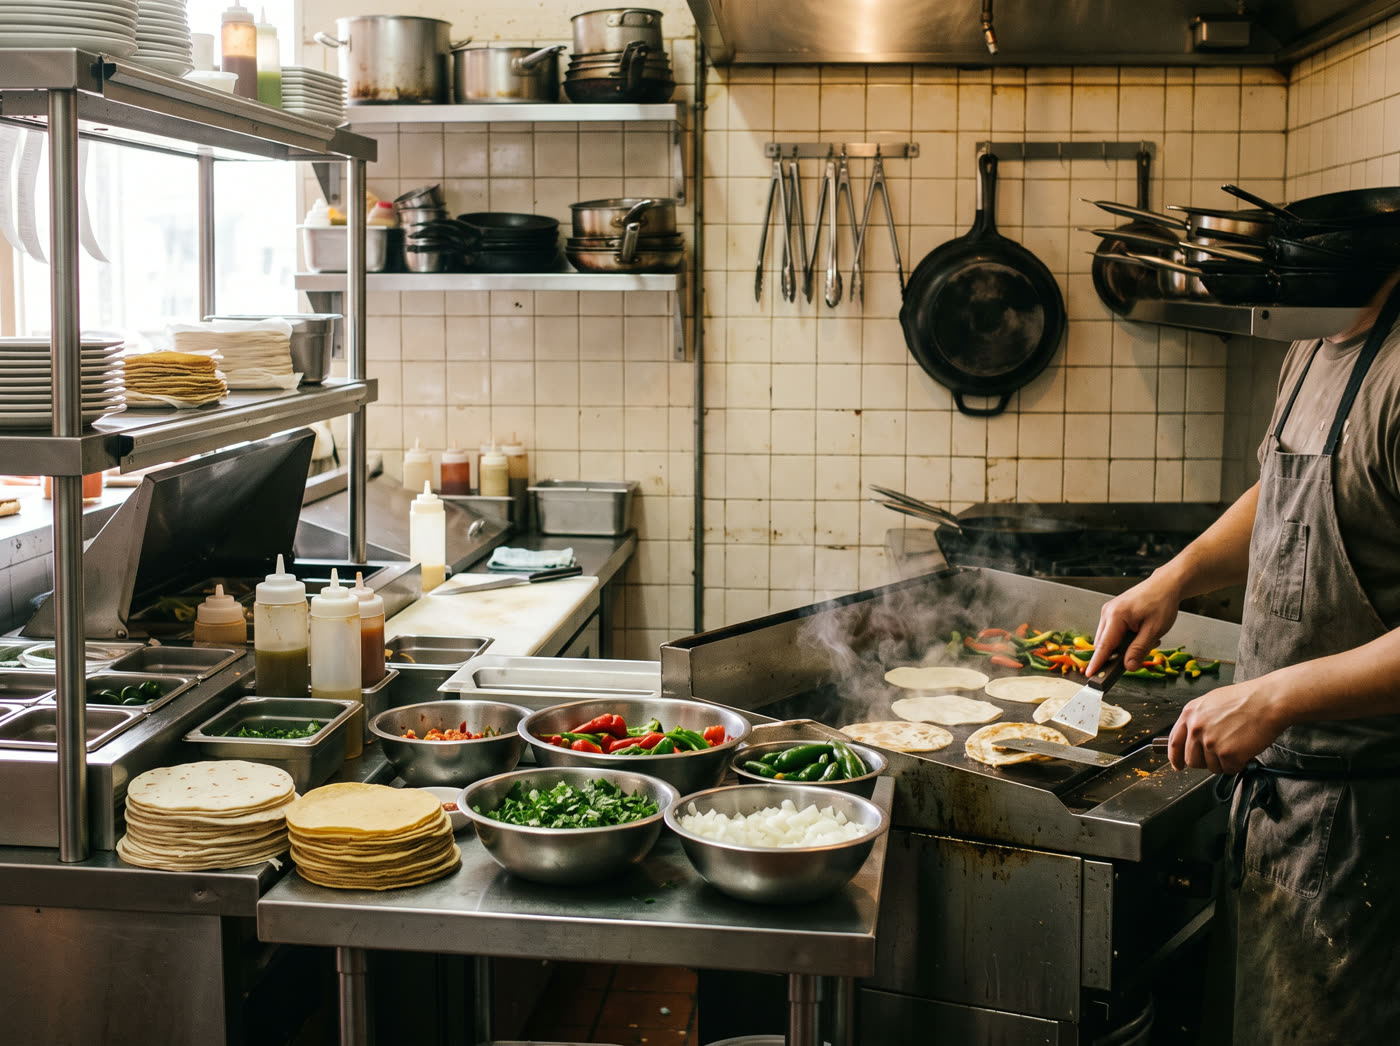
Kitchens and dining rooms
Property, liquor liability, spoilage, business income.
Clinics and practices
Professional liability, cyber, property, BOP.
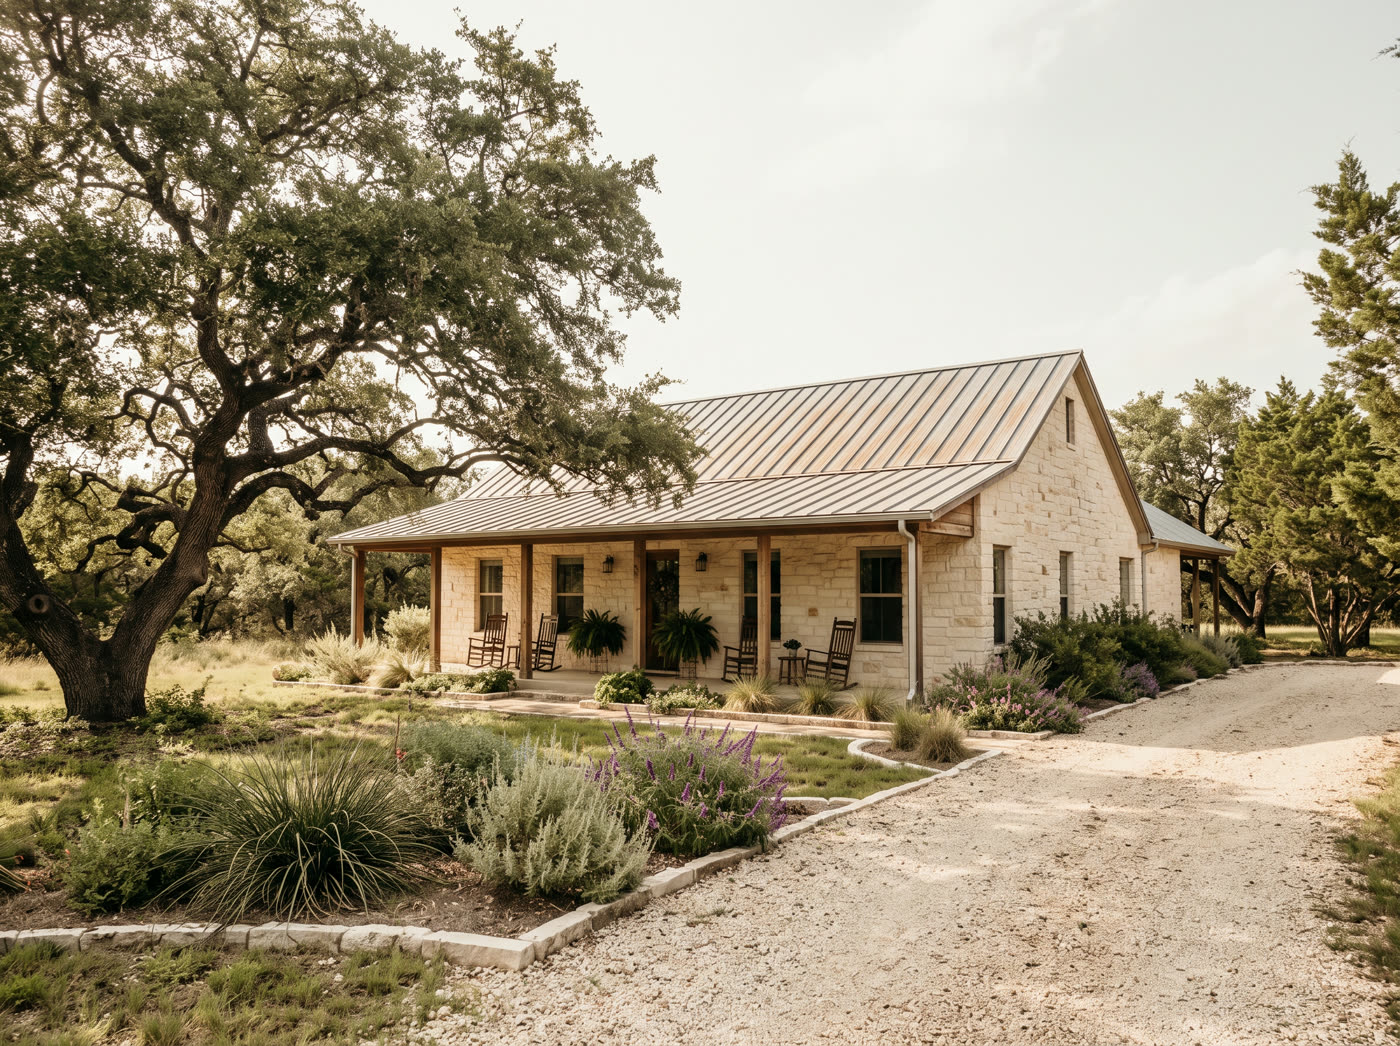
For your household
Home, auto, renters, life and umbrella, bundled simply.
Find the gaps before a claim does.
Four quick questions. You will see the coverage most businesses like yours need, with one line on what each one actually does.
Most surprises we see come from three places: a work truck on a personal policy, tools left off the policy, and a hail deductible nobody read. This check catches all three.
General guidance only. Your quote is based on your actual operations.
What kind of work do you do?
How many people work for you?
Do you use any vehicle for work, even your own truck?
Where does the work happen?
A local advisor, not a call center.
“I have sat across from owners who found out at claim time that a $400 add-on would have saved them $40,000. That is why I read the whole policy with you.”
Marrium Sohail started the agency for San Antonio business owners who want coverage explained plainly and handled personally. She knows the construction corridors, the restaurant blocks, the clinics near the Medical Center, and the ranch roads past Loop 1604.
Three options, one recommendation.
No pressure, no jargon. Here is what happens after you call.
One call
Ten minutes about your work, your vehicles, your space and your people. We ask so the quote is right the first time.
We compare
We take your details to multiple A-rated carriers. You do not fill out five applications.
We explain
Three options side by side: what each covers, what it costs, and which one we would pick and why.
We stay
Certificates, changes, renewals and claims go through the same advisor. You call one number.
Local risk is specific. So is our advice.
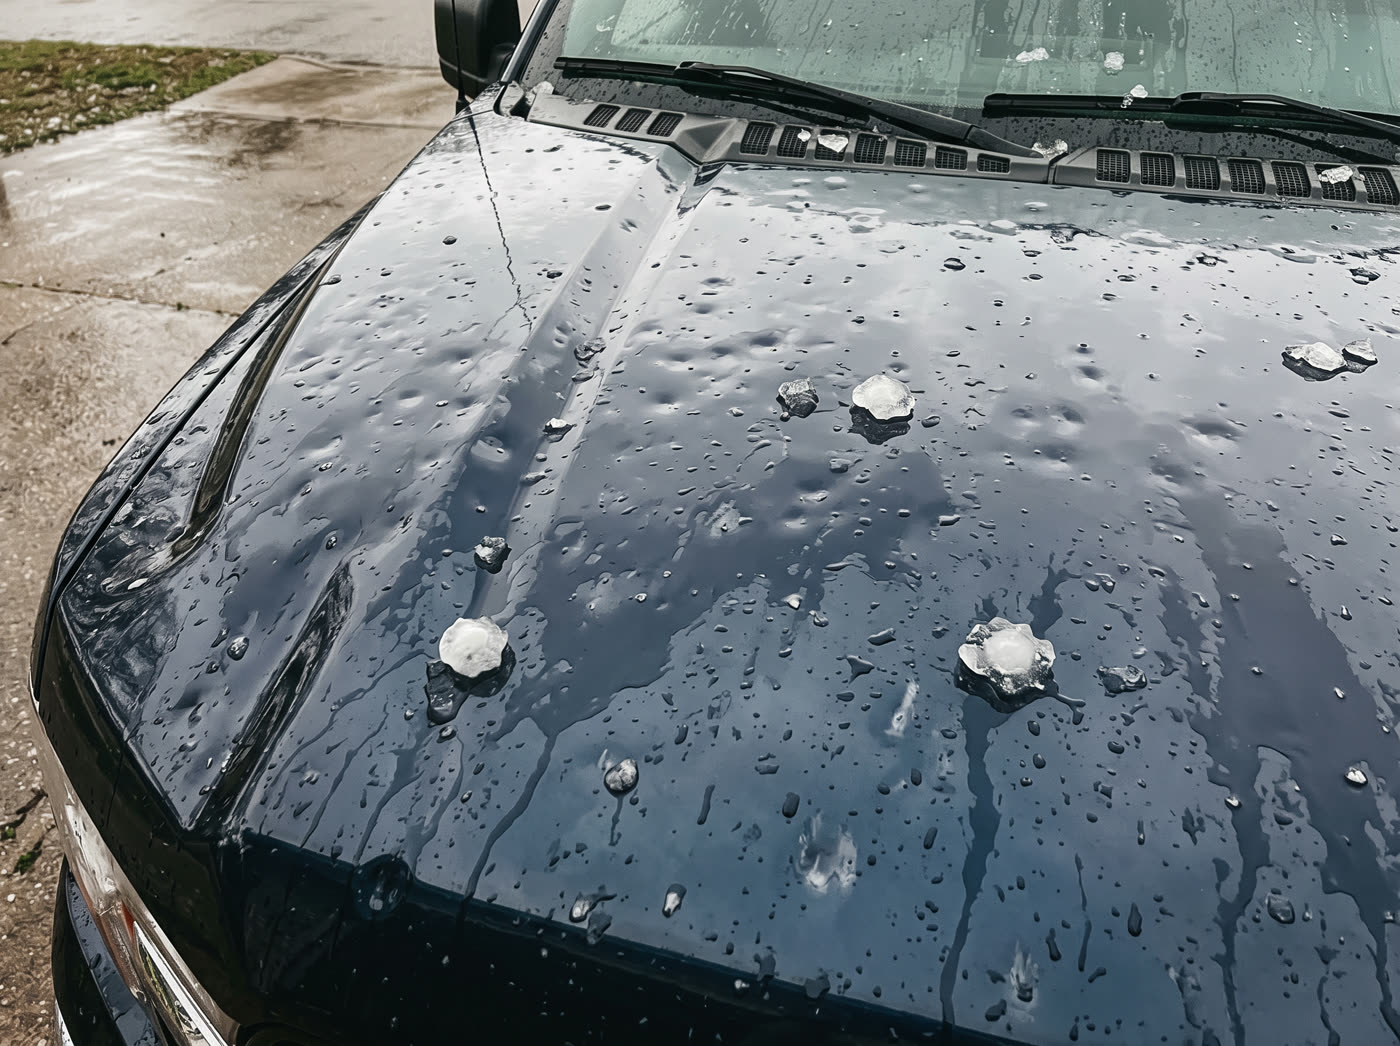
Hail is the number one property claim in Bexar County. Here is how we plan for it and the rest of what Texas brings.
- Hail and wind. Many Texas policies use a percentage deductible. On a $400,000 building, 2% is $8,000. We show you that number up front.
- Flash flooding. Standard home and business policies exclude flood. Flood coverage usually has a 30-day wait, so it is a spring conversation, not a storm-week one.
- Workers' comp is optional in Texas. Optional is not the same as safe. Without it, an injured employee can sue you directly.
- Work trucks. If your truck is in your name but used for jobs, your personal auto policy probably will not cover a work accident.
advisor you talk to, from quote to claim
options in every quote, with one recommendation
target to file your claim with the carrier
cost for a policy review, even if you stay where you are
[Sample reviews to show layout — replace with real client reviews before launch]
Questions owners ask us every week.
Every term explained the first time it shows up.
See all answersWe are not tied to one insurance company. We compare several carriers for you and recommend the one that fits, then stay your contact if you switch carriers later.
Texas is the only state where most private employers can choose not to carry it. If you opt out, you lose legal protections and an injured worker can sue you directly. Many general contractors and public contracts also require it.
A deductible is what you pay before insurance kicks in. On Texas property policies the wind and hail deductible is often a percentage of the building's insured value, so check the dollar amount, not just the percentage.
Usually the same business day. A certificate of insurance is a one-page proof of coverage that general contractors, landlords and clients ask for. Call or email us with who needs it and we send it directly.
Straight answers about your coverage, usually the same day.
One call. We compare real options from multiple carriers and explain what each one covers, in plain words.